Building a successful business is one thing. Knowing when to step away from it, and whether you can afford to, is quite another.
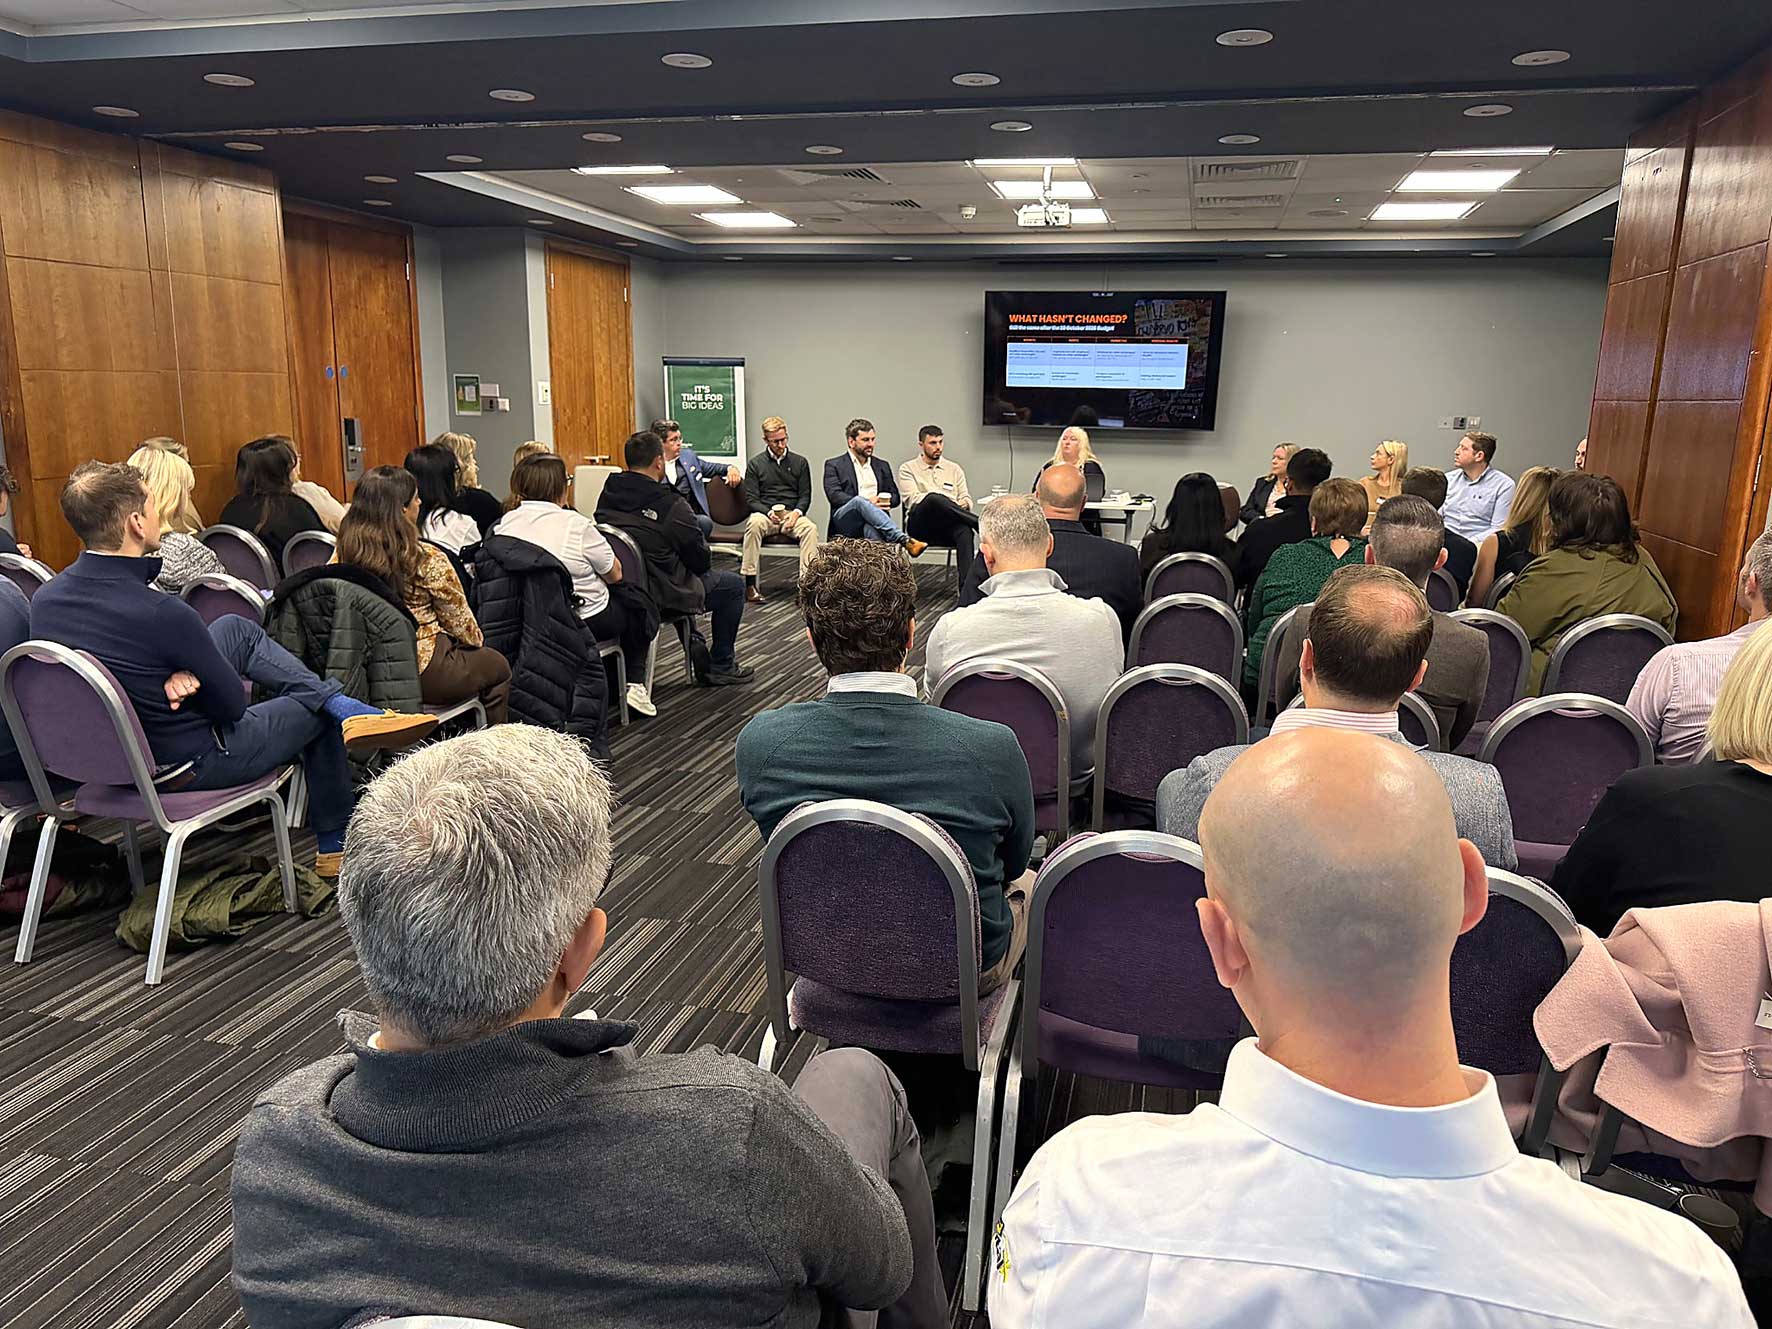
Those questions were at the heart of a Budget briefing hosted by accountancy and business advisory firm TC Group in Milton Keynes this week, where specialists challenged business owners to look beyond the Chancellor’s announcements and consider the decisions that could shape their financial futures.
Rather than concentrating on tax rates and thresholds, the discussion at the Holiday Inn in central Milton Keynes followed the life of a business, from its earliest days through growth, succession and eventual sale.
And one of the most interesting questions was not how much tax an owner might pay when selling, but whether they actually needed to sell at all.
For many entrepreneurs, the business represents years of hard work, financial risk and personal sacrifice. It may also be their largest asset and the foundation of their retirement plans. Yet decisions made long before a sale is contemplated can have a significant bearing on how much of that value they eventually realise.
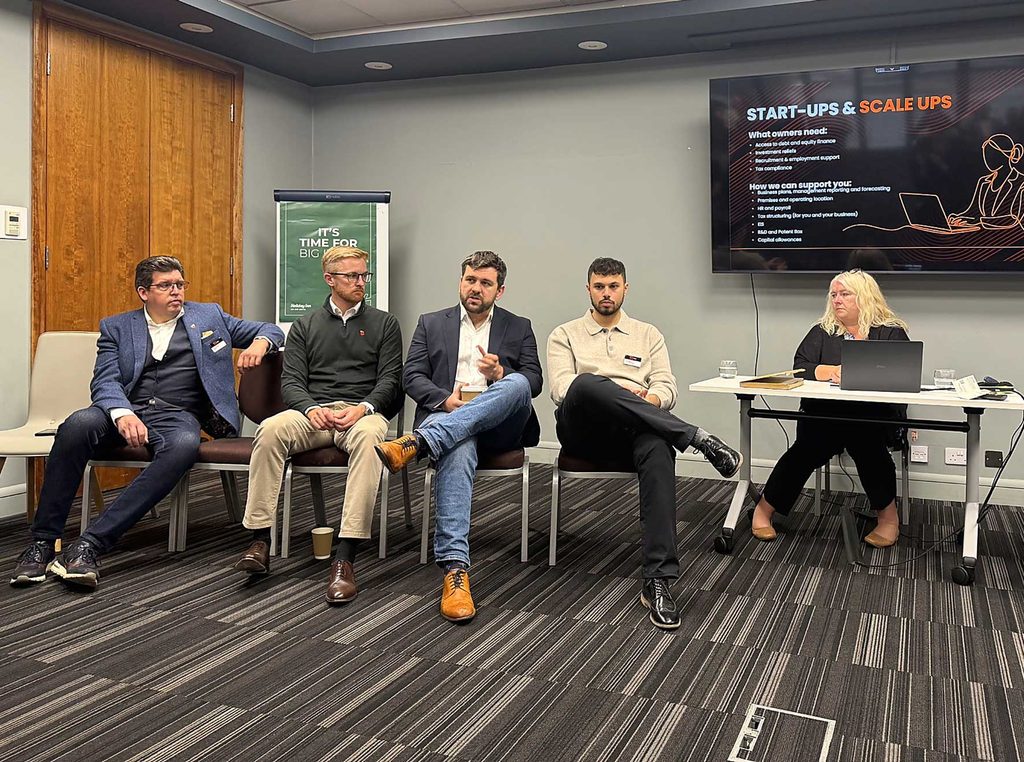
Introduced by Debbie Ince, the TC Group panel brought together specialists in tax, corporate finance, research and development, payroll, HR and financial planning.
Following a short review of the Budget announcements by Luke Wrightson, the discussion turned to practical case studies examining how the changes could affect owner-managed businesses at different stages of development.
The first consideration was getting the foundations right.
Employment contracts, ownership arrangements and the structure of a business may not be priorities for entrepreneurs concentrating on winning customers and establishing themselves. But overlooking them can create difficulties as a company grows.
Bruce Kier, who leads TC Group’s outsourced HR service, highlighted the problems that can arise when businesses adopt employment contracts or staff handbooks from previous organisations without fully understanding the obligations they create.
As companies expand, those arrangements can become increasingly difficult to change, particularly against a backdrop of employment law reform.
Estelle Sherman, TC Group’s head of payroll, reinforced the importance of accurate employment records and ensuring payroll arrangements reflect contractual terms.
The discussion also explored the risks associated with treating workers as self-employed contractors when the reality of their working relationship may indicate employment.
Debbie Ince and tax adviser Jennie Brown examined the complexities of IR35 and employment status, including the potential consequences for businesses that incorrectly classify workers.
Unpaid tax, National Insurance contributions and employment-related liabilities can remain undiscovered for years, only to emerge when a prospective buyer begins examining a company’s records.
It was an example of how a decision made to solve an immediate problem can have consequences much further down the line.
As businesses mature, the challenges change. Founders may have built successful companies but find themselves increasingly responsible for every important decision.
Retaining talented managers and giving them a greater stake in the business can help reduce that dependence.
Patrick Faughnan, TC Group’s head of corporate finance, discussed Enterprise Management Incentive share option schemes as a way for qualifying businesses to reward key employees and potentially prepare the ground for a future management buyout.
For an owner considering stepping back, a capable management team can be valuable in its own right. It may also make the business more attractive to an external purchaser who wants confidence that the company can continue operating successfully without its founder.
But knowing when to sell, and what the business might command, presents another challenge.
Patrick explained that owners frequently begin thinking about succession several years before they intend to leave, without necessarily knowing the current value of their company or what might increase it.
Customer concentration, reliance on particular suppliers, property ownership and dependence on individual directors can all affect a valuation.
A business generating healthy profits may still be less attractive to a buyer if too much of its income comes from one customer or its success depends heavily on the continued involvement of its owner.
The discussion also explored the changing tax treatment of business sales, including Business Asset Disposal Relief and Employee Ownership Trusts.
Although tax changes can create pressure to complete a transaction before a deadline, the panel cautioned against allowing that pressure to dictate the timing of a sale.
Securing a better price, improving the company’s financial position or resolving issues that might concern a purchaser could outweigh the benefit of completing a deal earlier to secure a particular tax rate.
Preparation was a recurring theme.
Jennie Brown explained that some tax reliefs depend on ownership arrangements having been in place for a qualifying period. Restructuring a group of companies, separating property from trading activities or introducing new shareholders may also require careful planning.
By the time an offer arrives, some opportunities may already have been lost.
The same principle applies to research and development tax relief.
Felix Medd, TC Group’s head of R&D, discussed changes intended to simplify the claims process, particularly for start-ups and growing businesses that may previously have missed notification deadlines.
He also stressed the importance of maintaining evidence to support claims.
For a business preparing for sale, unresolved tax enquiries or inadequate records can become a negotiating issue, potentially affecting the price a buyer is prepared to pay.
Patrick described an example involving a technology business approached by an overseas purchaser. Identifying previously unclaimed R&D relief before the sale could allow the owners to recover value that might otherwise have been overlooked.
Yet the discussion moved beyond the mechanics of building and selling a business to something more personal.
For entrepreneurs who have spent much of their working lives developing a company, there can be an assumption that its eventual sale will provide the money needed for retirement.
That approach carries risks.
Sam Whatsize, an independent financial adviser with TC Financial Planning, told the audience: “A lot of people look at their business as their pension or their kind of major level of wealth. But these can go wrong and things can change.”
He explained that moving some wealth out of a business and into personal investments or pensions can help reduce reliance on a single asset.
Company pension contributions, commercial property held within pension arrangements and other forms of financial planning were discussed as ways of building financial security alongside the business.
But the wider question was whether owners have a clear understanding of what they actually need their money to achieve.
A business might be worth several million pounds, but that figure alone says little about whether its owner can afford to retire, support their family or pursue other ambitions.
Equally, someone who believes they must continue working for another five or ten years may already have accumulated sufficient wealth to make a different choice.
Financial forecasting can help establish what an owner needs, taking account of personal assets, future expenditure and the lifestyle they want to maintain.
Sam posed a question that cut through much of the technical discussion.
“If you can do everything you want to in life with the money today, would you not want to know that?”
He added: “If you do then decide to carry on working, you know it’s a choice. It’s not a must to continue to work.”
It was a reminder that business succession planning is not simply about maximising a sale price. It is also about understanding what happens afterwards.
The panel also considered the importance of protecting the wealth and businesses that owners have created.
Responding to a question about wills and inheritance tax, Jennie highlighted the need for personal and business arrangements to work together.
Wills, shareholder agreements and lasting powers of attorney can all play a part in protecting a company and ensuring its continuity if an owner dies or becomes unable to manage their affairs.
Patrick also raised shareholder protection insurance, which can provide the funds needed for surviving shareholders to purchase a deceased partner’s interest in the business.
Without appropriate arrangements, a company could face difficult questions about ownership and control at an already challenging time.
Inheritance tax planning has also become increasingly important for business owners considering a sale. The tax position of an individual can change substantially when a qualifying business interest is converted into cash.
There were more immediate issues for employers to address, too.
Estelle highlighted National Minimum Wage compliance and the importance of reviewing payroll records, particularly where salary sacrifice arrangements or deductions could result in employees receiving less than the statutory minimum.
With enforcement activity placing increasing responsibilities on employers, businesses were encouraged to review their arrangements rather than assume that paying the published hourly rate automatically guarantees compliance.
The implications extend beyond avoiding penalties. Employment disputes, incomplete payroll records and unresolved tax enquiries can all complicate negotiations when a business is put up for sale.
What emerged from the TC Group briefing was a picture of business planning in which relatively small decisions, taken at different stages, can have a cumulative effect on the eventual outcome.
The choice of company structure at the beginning, the way employees are recruited and rewarded, the management team developed along the way and the protection put around personal wealth can all influence what an owner is ultimately able to achieve.
And while Budgets will continue to change tax rates, reliefs and allowances, those wider considerations remain.
For business owners, the challenge is not simply to build a company worth selling. It is to understand what they want from it, how much they need and whether the decisions they are making today will give them those choices when the time comes.